How Curiosity, Persistence, and Patience Find Small-Cap Stars Most Investors Miss

October 21, 2026

download document icon

Behind Formula One’s glamour, Langdon found DO&CO, an Austrian catering business with compounding potential. Greg Dean explains how curiosity, five years of research and patience on valuation helped uncover an opportunity for the Global Smaller Companies Portfolio.

 How Curiosity, Persistence, and Patience Find Small-Cap Stars Most Investors Miss How Curiosity, Persistence, and Patience Find Small-Cap Stars Most Investors Miss How Curiosity, Persistence, and Patience Find Small-Cap Stars Most Investors Miss How Curiosity, Persistence, and Patience Find Small-Cap Stars Most Investors Miss

How Curiosity, Persistence, and Patience Find Small-Cap Stars Most Investors Miss

October 21, 2026

Behind Formula One’s glamour, Langdon found DO&CO, an Austrian catering business with compounding potential. Greg Dean explains how curiosity, five years of research and patience on valuation helped uncover an opportunity for the Global Smaller Companies Portfolio.

 How Curiosity, Persistence, and Patience Find Small-Cap Stars Most Investors Miss How Curiosity, Persistence, and Patience Find Small-Cap Stars Most Investors Miss
 How Curiosity, Persistence, and Patience Find Small-Cap Stars Most Investors Miss How Curiosity, Persistence, and Patience Find Small-Cap Stars Most Investors Miss

How Curiosity, Persistence, and Patience Find Small-Cap Stars Most Investors Miss

October 21, 2026

download document icon

Behind Formula One’s glamour, Langdon found DO&CO, an Austrian catering business with compounding potential. Greg Dean explains how curiosity, five years of research and patience on valuation helped uncover an opportunity for the Global Smaller Companies Portfolio.

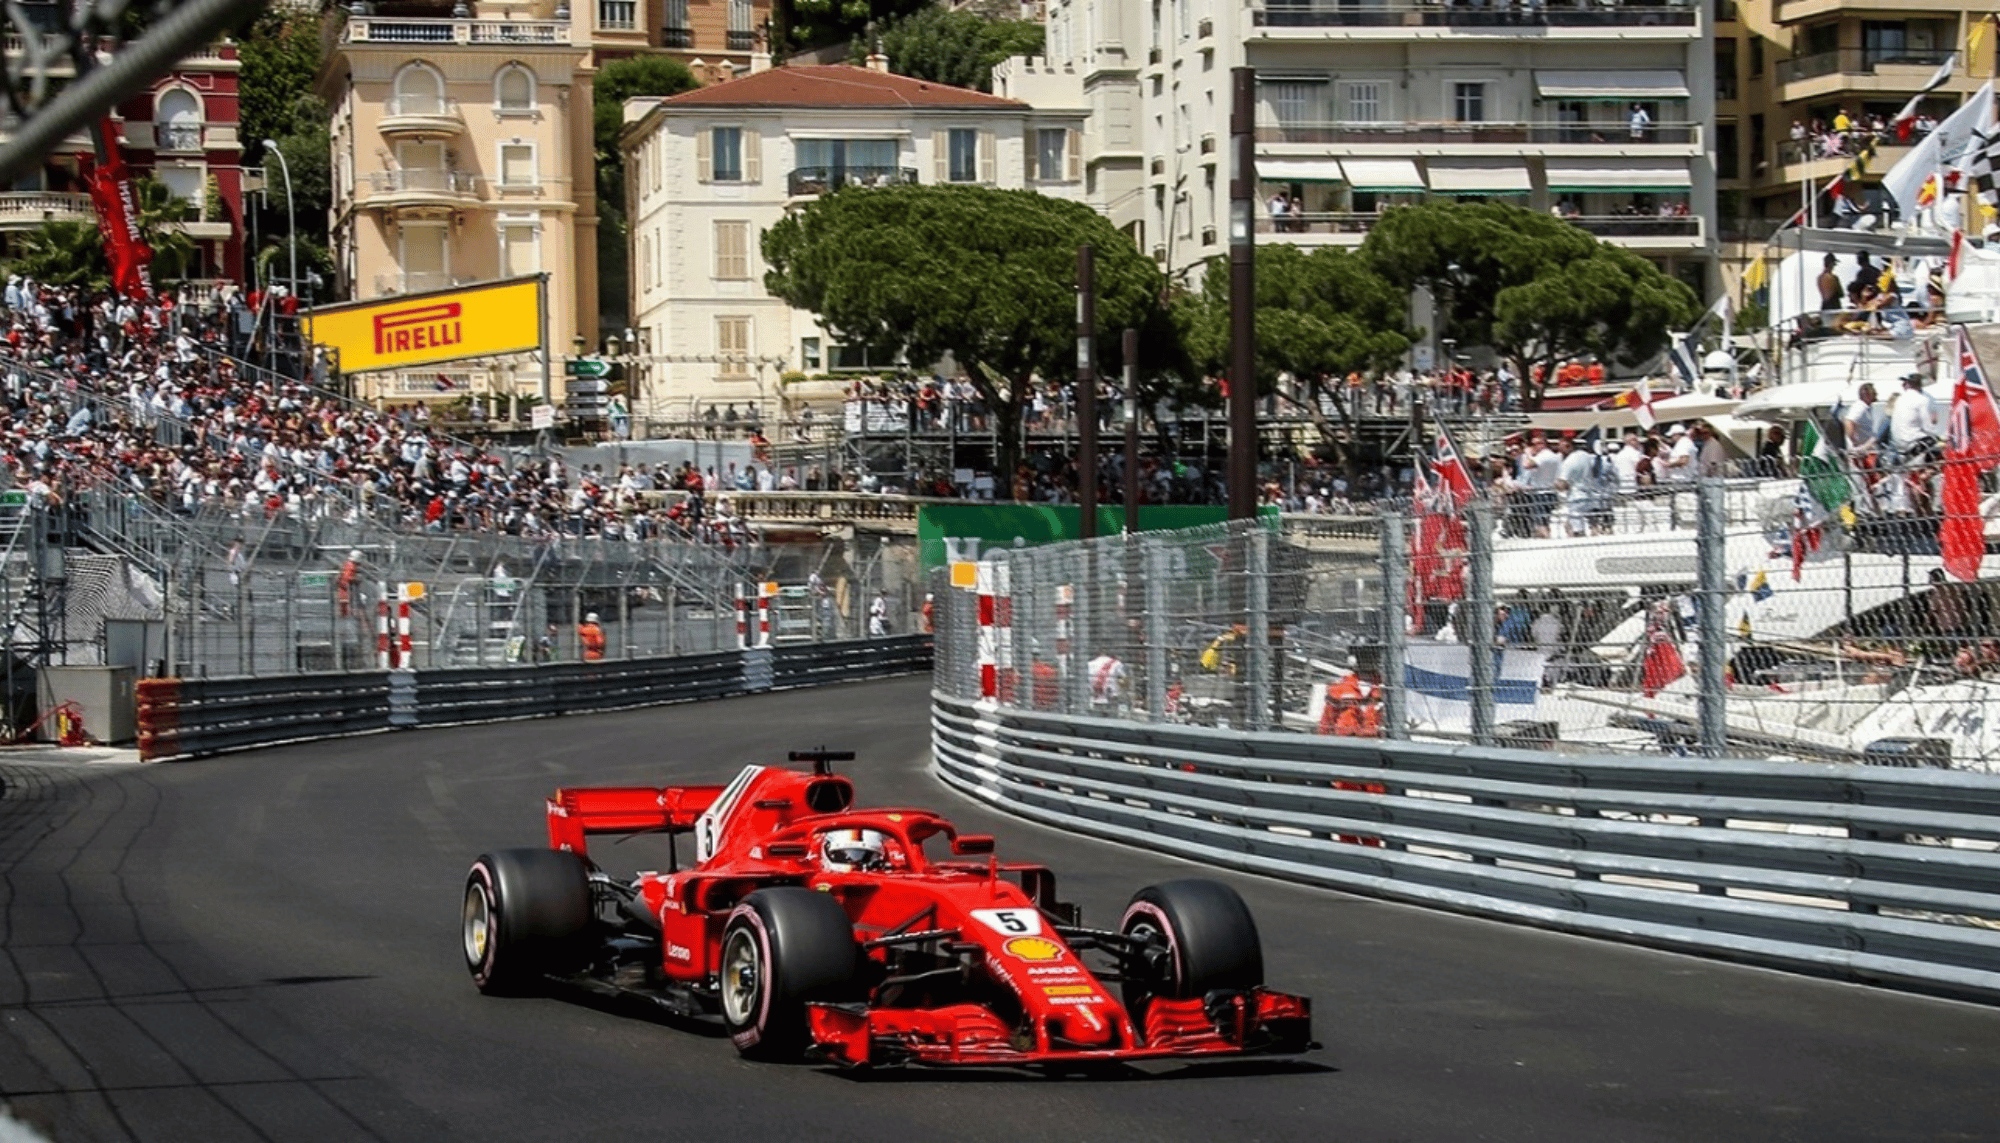
Formula One has been a roaring success since Liberty Media took the wheel in 2017. Netflix’s gripping Drive to Survive docuseries, spectacular new races in Miami and Las Vegas, and on-the-pulse digital marketing have attracted a global fan base of 826.5 million. Investors who bought Liberty Media’s Formula One Group shares following the 2017 acquisition have earned annualized total returns of around 17%.

Langdon Equity Partners went behind the scenes at Formula One and discovered DO&CO: an Austrian small cap it believes is even better.

Greg Dean, Founder and Lead Investor at Langdon Equity Partners, explains how curiosity, persistence, and patience led his team to add this potential compounder to the firm’s Global Smaller Companies Portfolio. To learn more about Langdon’s distinct investment approach and perspective on DO&CO, watch Greg Dean’s presentation at an investment conference.

A long-Shot email leads to a Small-Cap compounder

It was René Berger, the business partner of Mercedes Formula One boss Toto Wolff, who started me on the trail. Early in 2020, on my way to an investment conference in Bad Ragaz, Switzerland, I discovered that René and Toto were investing in Swiss small caps. As a small-cap enthusiast, I wanted to know more. I also had another motive. I’d been tracking Formula One since the Liberty Media investment, and I thought I might pick up some scuttlebutt.

So instead of flying from Munich to Zurich for the conference, I changed my ticket and flew to Vienna. From the hotel, I sent René a cold email. It was a long shot, but he replied. I extended my stay and met him at his office a few days later.

During our meeting, René mentioned that one of their investments was a small-cap broker in Vienna and suggested we connect. I was hooked. I extended my stay again and met the firm’s head for lunch. Their top recommendation: DO & CO.

I’d never heard of the company. Shocking, because DO & CO are the caterers for Formula One. They’ve been serving gourmet food to drivers, teams and VIPs since Niki Lauda recommended them to motorsport kingpin Bernie Ecclestone in 1992.

So my 700-kilometre detour, several extensions to my trip, a hunch about small caps, and curiosity about what goes on behind the scenes at Formula One delivered an opportunity. But it wasn’t love at first sight.

Back in Toronto, I did some digging. DO &CO IPO’d in Vienna in 1998 with a market cap of around €100 million. By 2020, they were generating close to €1 billion in revenue. EBITDA margins were around 12%, but free cash flow was almost nonexistent. They were investing heavily in rolling out infrastructure.

Formula One wasn’t DO & CO’s main business. That was prestigious, yes. But about 80% of revenue came from airline catering. The company provides premium meals to more than 60 airlines, including Delta, Emirates, Cathay Pacific, Singapore, British, and Turkish Airlines. Niki Lauda knew all about DO & CO because they’d been feeding his passengers on Lauda Air for years.

The Business Model Offers Meaningful Return on Capital

When I looked at DO & CO’s business model, I realized how smart it was. They underwrite a kitchen investment for an anchor airline and initially target a 3- to 4-year payback. As they , such as other airlines, local restaurants, and event venues, the returns from that kitchen can increase meaningfully.

But 2020 was the worst year in airline history. COVID-19 pulled the plug on international travel. Airlines lost more than $126 billion. When I pitched Do & Co to the team, we judged the downside risk too high and held off.

Over the next five years, we continued to meet with Do & Co and followed the business closely. Our interest in undertaking further work on the company was catalyzed by a meeting in London, where our key takeaway was that free cash flow generation had the potential to unlock value for the first time in decades.

Many fund managers will tell you they do this kind of research. And some do. But we dug deep. We didn’t just track the CEO and CFO. We studied the top 20 managers and looked at their performance, tenure, and rotation through the business. That tells you about commitment and depth of management. Attila Doğudan, the founder and CEO of DO & CO, still owns 30% of the company, and most of his managers have been around him for a long time.

Over those five years, we met management more than 25 times, attheir offices, on kitchen tours, and at an AGM. We got to know Attila and hissons, who are also involved in the business.

Throughout this period, we continued to watch for a dislocation between Do & Co’s value and its share price. We stayed patient. It’s one thing to identify a great company; if the price isn’t right, it’s not a great investment.

The decision to increase our position

In 2025, we were already shareholders in Do & Co when broader equity markets sold off amid rising concerns around U.S. tariffs. As anxiety gripped markets, airline-related stocks were hit particularly hard due to worsening sentiment around North American travel demand. Despite having limited direct exposure to the disruption, Do & Co’s share price declined by approximately 20%, which we viewed as an opportunity to increase our position.

This decision reaffirmed our conviction in a business we hadoriginally invested in at an implied 8%–9% free cash flow yield (equivalent toroughly 11–12× free cash flow). At the time, the company carried no debt,capital was well deployed, and growth remained intact. Do & Co has since delivereda five‑year CAGR of over 20%, accelerating to more than 36% in 2024. We believethe company has the potential to deliver strong compound returns for many yearsto come.

disclaimer

This article is prepared by Langdon Equity Partners. Content in respect of the Langdon Smaller Companies Fund (ARSN 657 901 614 (the Fund) is issued by Pinnacle Fund Services Limited ABN 29 082 494 362 AFSL 238 371 (‘PFSL’) as responsible entity of the Fund. PFSL is not licensed to provide financial product advice. It contains general information only. It is not intended as a securities recommendation or statement of opinion intended to influence a person or persons in making a decision in relation to investment. It has been prepared without taking account of any person’s objectives, financial situation or needs. Any persons relying on this information should obtain professional advice before doing so.

Past performance is for illustrative purposes only and is not indicative of future performance.

While Langdon Equity Partners Limited (‘Langdon’) and PFSL believe the information contained in this communication is reliable, no warranty is given as to its accuracy, reliability or completeness and persons relying on this information do so at their own risk. Subject to any liability which cannot be excluded under the relevant laws, Langdon and PFSL disclaim all liability to any person relying on the information contained in this communication in respect of any loss or damage (including consequential loss or damage), however caused, which may be suffered or arise directly or indirectly in respect of such information. This disclaimer extends to any entity that may distribute this communication.

FOR AUSTRALIAN CLIENTS:

The Product Disclosure Statement (‘PDS’) and Target Market Determination (‘TMD’) of the Fund are available via the links below. Any potential investor should consider the PDS and TMD before deciding whether to acquire, or continue to hold units in, the Fund.

Link to the Product Disclosure Statement: here

Link to the Target Market Determination: here

For historic TMD’s please contact Pinnacle Client Service Phone 1300 010 311 or Email service@pinnacleinvestment.com  

FOR CANADIAN CLIENTS:

Important information about each Langdon mutual fund is contained in its prospectus, AIF, fund facts document and in its management report on fund performance. Any potential investor should review these documents prior to making any investment decision relating to such fund.  You can view copies of these documents by following the links below:

Link to the Langdon Global Smaller Companies Portfolio Disclosure Documents: here

Link to the Langdon Canadian Smaller Companies Portfolio Disclosure Documents: here